
In the 28 July post, we introduced the IPSASB’s proposal to introduce more structure to the Statement of Financial Performance. In this post, we consider whether the proposed categorisation, totals and subtotals in the Statement of Financial Performance would provide better information to users.
Categorisation
A key proposal is to group revenue and expenses into categories such as operating, investing, financing, income tax and discontinued operations, to distinguish core service delivery (i.e. operating activities) from other activities. The proposed categories are aligned with IFRS 18 Presentation and Disclosure in Financial Statements, with additional public sector guidance. The aim is to make financial performance easier to analyse, for example, by separating taxes and service delivery costs from investment returns or borrowing costs.
Totals and subtotals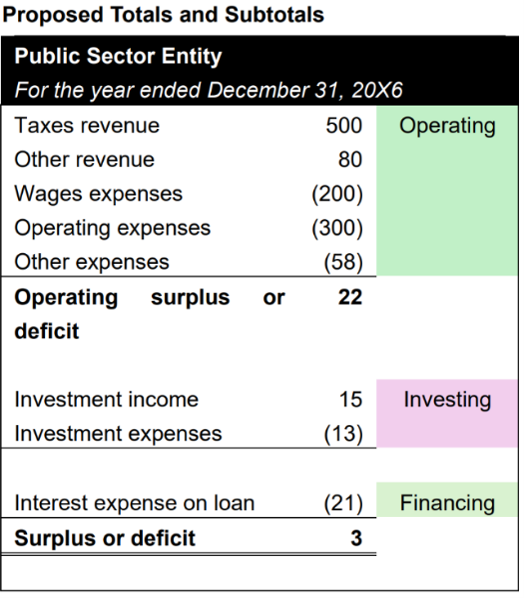
The IPSASB is proposing the addition of an operating surplus or deficit subtotal. Operating surplus or deficit is defined as all revenue and expenses in the operating category, and surplus/deficit is retained as a total across all categories. This operating surplus or deficit subtotal is intended to show whether operating revenue is sufficient to sustain service delivery, which would also correlate with the categorisation proposal above.
However, these proposals raise important questions. The categories are derived from IFRS 18, and the introduction of an operating subtotal may be interpreted in a way similar to operating profit. The concern is whether this introduces a profit-oriented lens into public sector reporting, rather than reflecting service delivery.
In the next article, we consider how detailed the Statement of Financial Performance should be, and where the balance between structure and flexibility should lie.
Share your comment
 The ASB is consulting locally through ED 221 to gather input that will inform South Africa’s response to the IPSASB’s proposals. The matters discussed above relate to Preliminary Views 8 and 9 in the Consultation Paper. To get invited to the roundtable discussions or share your written input, send an email to info@asb.co.za or siyasangan@asb.co.za before the comment deadline of 31 August 2026.
Disclaimer
The article has been prepared by the Secretariat of the ASB for information purposes only. It has not been reviewed, approved, or otherwise acted on by the Board.